Services
Your Roof Damage Insurance Claim in Miami
Dated photos, a written damage report and an itemized repair price for your roof claim. You and your insurer decide the claim.
Insurance claim paperwork
A roof damage insurance claim in Miami goes better with complete paperwork: what happened, when, what it broke and what the repair will cost under the hurricane code. That part we can help with. Deciding what the claim pays is between you and your insurer, and Florida law keeps roofers out of that conversation for good reasons. Here’s exactly what we provide and what we don’t.
What you get from us
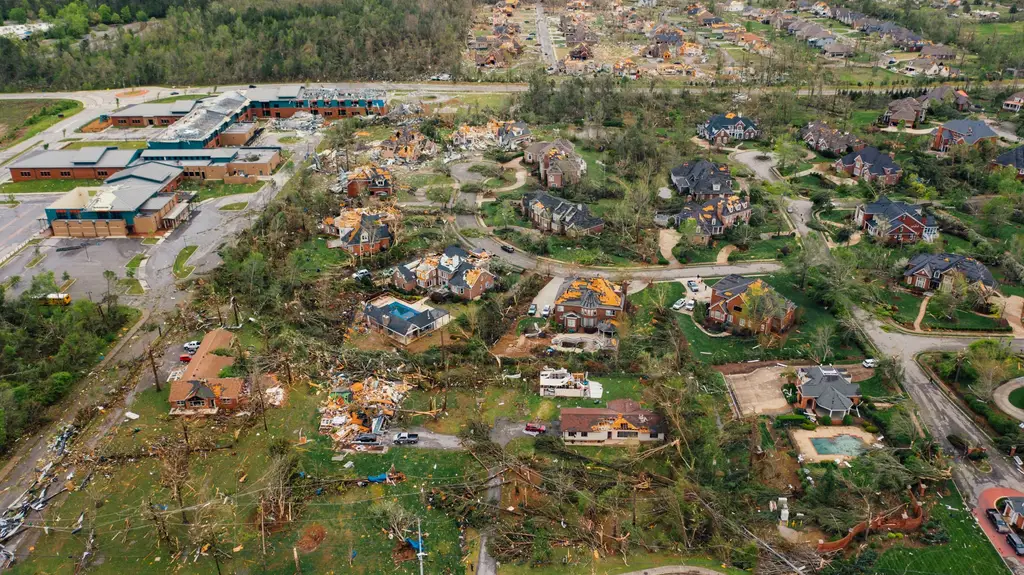
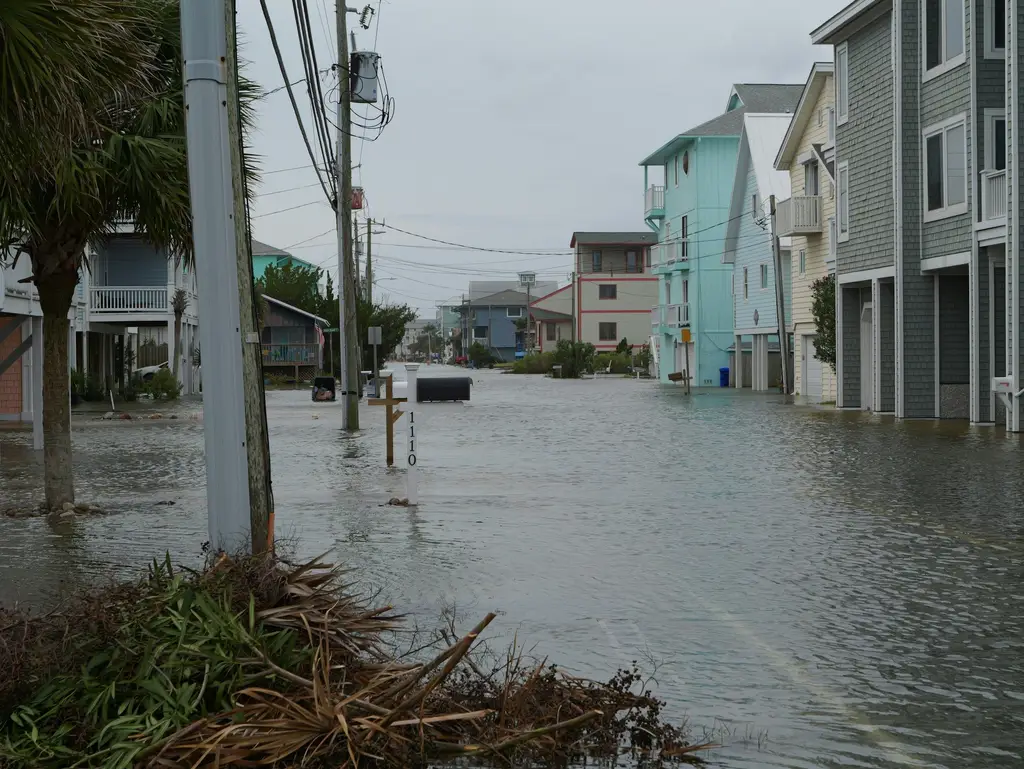
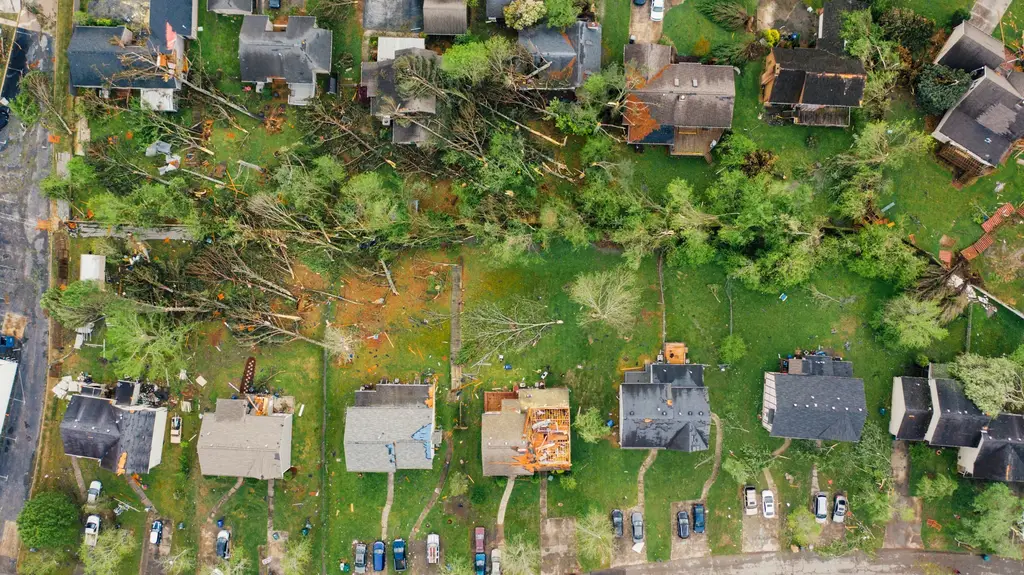
Photos with dates. Every sign of damage, close up and from far enough back that you can tell where it is on the roof. Broken tile, open seams, lifted panels, torn flashing, wet decking and the ceiling stains inside. Each photo carries the date it was taken.
A written damage report. Plain language, slope by slope. What’s damaged, what isn’t, and what we think caused it. We include the parts of the roof that came through fine, because a report that only lists problems is easier to question.
An itemized price. Florida requires a roofer to give you a written, itemized estimate before you sign a contract for repairs paid by a property insurance claim. Ours lists every line: tear-off, decking, underlayment, the roof covering, flashing, the permit and cleanup, with the approved products named. In the High Velocity Hurricane Zone a repair has to meet the same product and fastening rules as a new roof, and the price reflects that, so there are no surprises later.
Records of emergency work. If we tarp the roof or seal a leak before the permanent repair, you get photos of the damage before we covered it and an invoice for the work. Your insurer will want both.
What we won’t do
Florida’s rules on roofers and insurance claims are specific. They protect you from contractors who take over claims and leave homeowners with bills. So there are four things you’ll never hear from us:
- “Here’s what your policy covers.” Coverage is your insurer’s answer, not ours.
- “Let us talk to the adjuster about the money.” Negotiating or settling a claim for you is public adjusting, and we aren’t public adjusters.
- “We’ll take care of your deductible.” No waivers, no rebates, no gift cards, nothing of value for an inspection or a claim.
- “Just sign the benefits over to us.” Florida law voids an assignment of post-loss benefits on policies issued on or after January 1, 2023, and we wouldn’t ask for one anyway.
Why the price matters to the claim
Adjusters usually price a roof with estimating software, and the hurricane zone adds costs that a generic estimate can miss: approved products, tighter fastening, tile set in adhesive and extra inspections. Our line-by-line price shows each of those, so you and your insurer are looking at the same roof.
If you want someone to handle the claim on your behalf, that’s the job of a licensed public adjuster or an attorney. We work alongside whoever you choose and give them the same photos and report we give you.
How the claim usually goes
- Protect the home. Get water stopped with a tarp or a temporary repair. Keep the receipts.
- Document the damage. We inspect and send you the photos and the written report.
- Report the claim. You contact your insurer and give notice. Florida gives you 1 year from the date of loss to do that, and 18 months for a supplemental claim from the same storm, but sooner is better.
- The adjuster visits. If you’d like us there, we’ll walk the roof with them and point out what we found.
- You get the insurer’s decision. If you have questions about it, those go to your insurer, a public adjuster or an attorney.
- The repair. Once you’ve decided to go ahead, we pull the permit and do the work at the written price.
When the insurer asks how old your roof is
Many Miami homeowners hear from their insurer as a roof gets older. Under Florida law, an insurer can’t refuse to write or renew a homeowner’s policy just because the roof is under 15 years old. If your roof is 15 years or older, you can have it inspected by an authorized inspector before you’re made to replace it, and if the inspection shows at least 5 years of useful life left, age alone can’t be the reason for a refusal. We can do that inspection and give you the report.
Discounts for a stronger roof
Florida requires insurers to offer discounts or credits for features that reduce wind damage, such as how the roof deck is attached and how the roof is tied to the walls. A wind mitigation inspection records those features on the state’s form. A new roof built to the hurricane code, with its permit and inspections on file, gives you more to show.
Where to start
If a storm just passed, start with a hurricane roof inspection. For a single leak, roof repair may be all you need, and for a roof that’s past fixing, see roof replacement. We provide claim paperwork across Miami, Hialeah and Coral Gables.
Insurance claim paperwork by town
- Insurance claim paperwork in Miami, FLBarrel tile in Little Havana, flat roofs on duplexes in Allapattah and metal on new builds near the river.
- Insurance claim paperwork in Hialeah, FLFlat and low-slope roofs on block homes, plus the shingle and tile roofs on Hialeah's newer streets.
- Insurance claim paperwork in Coral Gables, FLClay and concrete tile on Mediterranean homes, re-roofed to the city's design rules and the hurricane code.
Guides
Questions about insurance claim paperwork
Can you negotiate with my insurance company?
No. Under Florida law that's public adjusting, and only a licensed public adjuster or an attorney can do it for you. We stick to the roof, what's damaged, what the repair involves and what it costs, and you stay in charge of the claim.
Will you meet the adjuster at my house?
If you want us there, yes. We'll show the adjuster the damage we photographed and explain how the roof is built and what a proper repair involves under the hurricane code. Coverage questions are between you and your insurer.
Can you waive my deductible or give me a rebate?
No, and nobody else should either. Florida prohibits a contractor from offering to waive or pay a deductible, or from giving a rebate, gift or anything of value for an inspection or a claim. If someone offers, that's a warning sign.
How long do I have to report roof damage?
Florida law gives you 1 year from the date of loss to give your insurer notice of a property claim, and 18 months for a supplemental claim from the same event. Check your policy too, it lists other duties after a loss.